FHA loans do not carry PMI. They carry a mortgage insurance premium, or MIP, and HUD rules decide when it ends — not the federal law that governs private mortgage insurance on conventional loans.
For most FHA loans written since June 2013, the premium ends on a schedule fixed at origination, or through a refinance into a conventional loan, which turns on a current appraisal for mortgage refinancing.
FHA borrowers often pay premiums they assume appreciation will cancel. Home Value Inc. values Miami-Dade property for the refinance decision — check current value.
The premium on an FHA loan is not PMI, and the distinction decides the answer. Private mortgage insurance is a policy a conventional borrower buys from a private insurer, while the FHA mortgage insurance premium is charged by the Federal Housing Administration under HUD rules.
That difference changes both pricing and duration. A private insurer prices PMI against the borrower’s credit tier and loan-to-value band at closing, as the breakdown of how PMI is calculated sets out.
HUD sets MIP rates by mortgagee letter according to base loan amount, original loan-to-value and mortgage term, without reference to credit score, and collects an upfront premium of 1.75% of the base loan amount at closing on standard FHA purchase and refinance transactions, alongside the annual charge.
A homeowner asking whether PMI can be removed from an FHA loan is therefore asking whether MIP can be canceled. For most FHA borrowers with loans written in the past decade, cancellation on request is not available.
If you’re ready to get started, call us now!
The Homeowners Protection Act of 1998 governs private mortgage insurance on residential mortgage transactions, and FHA premiums sit outside it.
The 80% borrower-request right, the 78% automatic termination, and the amortization-midpoint termination described in the CFPB examination procedures all belong to conventional loans.
Three consequences follow for an FHA borrower in Miami-Dade County. No statutory right exists to request cancellation at 80%.
Paying the balance down faster does not trigger early cancellation on a post-2013 loan, because HUD does not permit early cancellation of annual MIP based on prepayment of principal.
And a servicer declining a cancellation request on such a loan is not refusing a federal right.
Advice written for conventional borrowers therefore transfers badly, since the thresholds, the request process, and the role of a new valuation all work differently, as the comparison of loan amount versus appraised value explains.
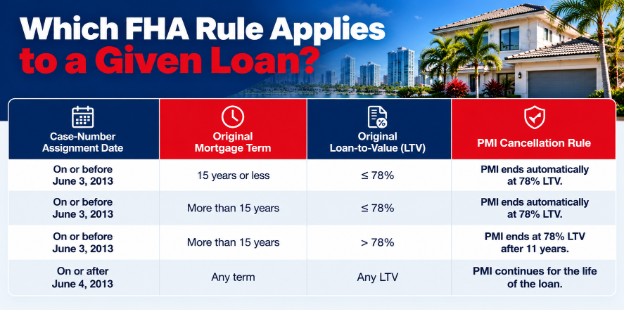
Duration depends on the date the FHA case number was assigned, the original loan-to-value ratio, and the mortgage term.
The table below outlines the rules governing loans closed on or after January 1, 2001, based on HUD guidance on MIP duration. Every date below refers to case-number assignment rather than closing or funding.
| Case Number Assigned | Mortgage Term | Original LTV | When Annual MIP Ends |
| Before June 3, 2013 | More than 15 years | Above 78% | Automatically at 78% LTV of the lesser of the initial sales price or appraised value at origination, after at least five years of annual MIP |
| Before June 3, 2013 | 15 years or less | Above 78%, up to 90% | Automatically at 78% LTV, with no minimum payment period |
| Before July 14, 2008 | 15 years or less | Below 90% | No annual MIP charged |
| On or after July 14, 2008, before April 18, 2011 | 15 years or less | 90% or below | No annual MIP charged |
| On or after April 18, 2011, before June 3, 2013 | 15 years or less | 78% or below | No annual MIP charged |
| On or after June 3, 2013 | Any term | 90% or below | After 11 years, or the mortgage term if shorter |
| On or after June 3, 2013 | Any term | Above 90% | Runs for the mortgage term |
Loans closed before January 1, 2001 fall under earlier rules and generally carry the premium for the loan term.
Mortgagee Letter 2013-04 closed the automatic-cancellation path for later case numbers, which is why an FHA borrower who bought in Miami-Dade after mid-2013 with a 3.5% down payment carries the premium for the life of the loan.
Four facts settle it, taken in order, and all four sit in the original closing package or the current mortgage statement.
No. The FHA schedules run on the original loan-to-value and the initial amortization schedule, so a property that appreciates does not reach an earlier cancellation date.
This is where FHA and conventional borrowers diverge most sharply. A conventional borrower whose Miami-Dade property has appreciated can ask the servicer to terminate private mortgage insurance on current value, a route the PMI removal appraisal page covers.
An FHA borrower has no equivalent request, so an appraisal ordered to prove appreciation on an FHA loan changes nothing by itself.
Current value still matters to an FHA borrower, but only through refinancing, where it becomes one of the figures deciding whether a new conventional loan carries mortgage insurance.
Appreciation does not shorten an FHA premium schedule. Home Value Inc. documents what a Miami-Dade property is worth now — get a value opinion.
A refinance replaces the FHA loan, so the FHA premium ends. The new conventional loan is underwritten against a fresh appraisal, and the appraised value sets the loan-to-value ratio that determines whether the replacement loan carries mortgage insurance.
The illustration below holds a $310,000 balance constant and varies the appraisal, assuming a conventional program that requires mortgage insurance above 80% loan-to-value. Actual requirements depend on the loan program, the lender, and the investor.
| Current Appraised Value | Resulting LTV | Mortgage Insurance Under the Assumed Program | Practical Outcome |
| $400,000 | 77.5% | Not required | Refinance ends the premium with margin to spare |
| $387,500 | 80.0% | Not required | Refinance clears the assumed threshold exactly |
| $360,000 | 86.1% | Required | Premium continues under conventional rules |
| $340,000 | 91.2% | Required, at a higher band | Refinance may not repay its closing costs |
Closing costs, the new interest rate, credit qualification, and the remaining term all affect whether the refinance makes sense, so a favorable valuation opens the option rather than settling it.
A borrower who believes a low report missed a relevant comparable sale can ask the lender to reconsider the value.
An FHA-to-FHA streamline refinance is a different transaction. It carries FHA mortgage insurance forward rather than ending it, though HUD’s refund schedule allows a portion of the unused upfront premium from the prior case to be credited toward the new one.
Three figures decide whether the refinance route is open, and establishing them before applying prevents a wasted application fee. Home Value Inc., a residential appraisal firm in Miami Springs, Florida, serving Miami-Dade County, produces the valuation that answers the middle one.
A pre-application value opinion and the lender’s appraisal are separate engagements, and they can land on different numbers.
The lender’s appraiser works to that lender’s scope and selects comparable sales as of the assignment date, so a market that moves between the two reports moves the second figure.
A pre-application report indicates whether an application is worth making; it does not bind the underwriting decision.
Borderline results deserve particular care. A property valuing within roughly 2% of the threshold has not cleared it in any dependable sense, because reasonable appraisers analyzing the same Miami-Dade comparable sales can differ by more than that margin, particularly on waterfront and condominium assignments where limited recent sales force a wider search.
A borrower in that position is usually better served by paying the balance down or waiting for further appreciation than by applying immediately.
Reports conform to the standards published by the Appraisal Standards Board.
Turnaround for a standard Miami-Dade residential property runs five to seven business days, with scheduling factors covered in the analysis of appraisal turnaround times, and preparation affects the result, as the walkthrough of preparing for a home appraisal sets out.
An automated online estimate does not substitute for either report, a limitation examined in the comparison of online property estimates against inspected valuations.
Can PMI be removed from an FHA loan?
FHA loans carry a mortgage insurance premium rather than PMI, and HUD rules govern it. For case numbers assigned on or after June 3, 2013, the premium ends on a fixed schedule or through a refinance into a conventional loan, not on request.
How long does FHA mortgage insurance last?
For case numbers assigned on or after June 3, 2013, annual MIP runs 11 years when the original loan-to-value was 90% or below, and for the mortgage term when it exceeded 90%. Earlier case numbers follow separate HUD rules.
Does the Homeowners Protection Act apply to FHA loans?
No. The Homeowners Protection Act governs private mortgage insurance on conventional loans. Its 80% request right, 78% automatic termination, and amortization-midpoint termination do not apply to FHA mortgage insurance premiums, which HUD administers separately.
Does rising home value or extra principal remove FHA mortgage insurance?
Neither does, for case numbers assigned on or after June 3, 2013. The duration runs on the original loan-to-value and the initial amortization schedule, and HUD does not permit early cancellation of annual MIP based on principal prepayment.
Which FHA loans still cancel automatically at 78%?
Loans closed on or after January 1, 2001 with case numbers assigned before June 3, 2013. On terms longer than 15 years, cancellation follows at least five years of annual MIP; on terms of 15 years or less, no minimum payment period applies.
Were some FHA loans never charged annual MIP?
Yes. Certain mortgages with terms of 15 years or less carried no annual premium, with the qualifying loan-to-value threshold varying by case-number window: below 90% before July 2008, 90% or below until April 2011, and 78% or below until June 2013.
Does refinancing always remove FHA mortgage insurance?
A refinance into a conventional loan below the program’s threshold generally removes it, subject to lender and investor requirements. An FHA-to-FHA streamline refinance carries FHA mortgage insurance forward rather than ending it.
What is the difference between MIP and PMI?
MIP is charged by the Federal Housing Administration on FHA loans under HUD rules, priced by loan amount, original loan-to-value, and term. PMI is bought from a private insurer on conventional loans and priced partly on the borrower’s credit tier.
Does an FHA borrower need an appraisal to cancel MIP?
No appraisal cancels MIP directly. An appraisal matters when the borrower refinances into a conventional loan, because current appraised value sets the new loan-to-value ratio that helps determine whether mortgage insurance applies.
Ending an FHA premium early runs through a conventional refinance. Home Value Inc. supplies the valuation that decision starts with — request a quote.
About the Author
South Florida Residential Appraiser · Expert Witness · Residential Valuation Specialist
Jhovan Rojas is a South Florida residential real estate appraiser with more than 20 years of experience valuing residential properties throughout Miami-Dade, Broward, and Palm Beach Counties. His appraisal experience spans multiple real estate market cycles, including the foreclosure-driven downturn of the late 2000s, the subsequent recovery period, and the rapid appreciation that followed the COVID-19 housing boom.
Throughout his career, Jhovan has appraised thousands of residential properties, including single-family homes, condominiums, multi-family residences, luxury estates, waterfront properties with boating access, and complex high-value residential assets. His expertise includes residential valuation, appraisal review, market analysis, lender compliance review, and expert witness services for litigation involving real estate valuation disputes.
In addition to performing residential appraisals, Jhovan has conducted appraisal reviews for lending institutions, supervised and mentored trainee appraisers, and provided expert testimony in divorce and property-related legal matters. He is also a frequent speaker for Realtor and broker education programs, where he shares insights on valuation methodology, appraisal standards, market trends, and factors influencing residential property values throughout South Florida.
Drawing on decades of hands-on appraisal experience, Jhovan helps homeowners, attorneys, lenders, real estate professionals, and property investors make informed decisions based on credible, well-supported valuation analysis.
Home Value Inc. performs residential and commercial appraisals for its clients in greater Miami-Dade County and the following cities in South Florida. We provide services to the following cities -