Reviewed by Jhovan F. Rojas, founder of Home Value Inc. and a Florida Certified Residential Appraiser (License RD6109) licensed since 2006.
A Miami-Dade property tax appeal is a petition to the Value Adjustment Board asking it to lower the market value the Property Appraiser placed on a parcel as of January 1.
The owner carries the burden of showing that figure is wrong, and a certified tax protest appraisal is one optional way to build that proof.
Petitions are due within 25 days after the August TRIM notice is mailed, with a $15 fee per folio.
Home Value Inc., a Miami Springs, Florida real estate appraisal firm, prepares these reports for owners across Miami-Dade County.
Miami-Dade owners who suspect an inflated assessment can request a free assessment review from Home Value Inc before the next petition window opens.
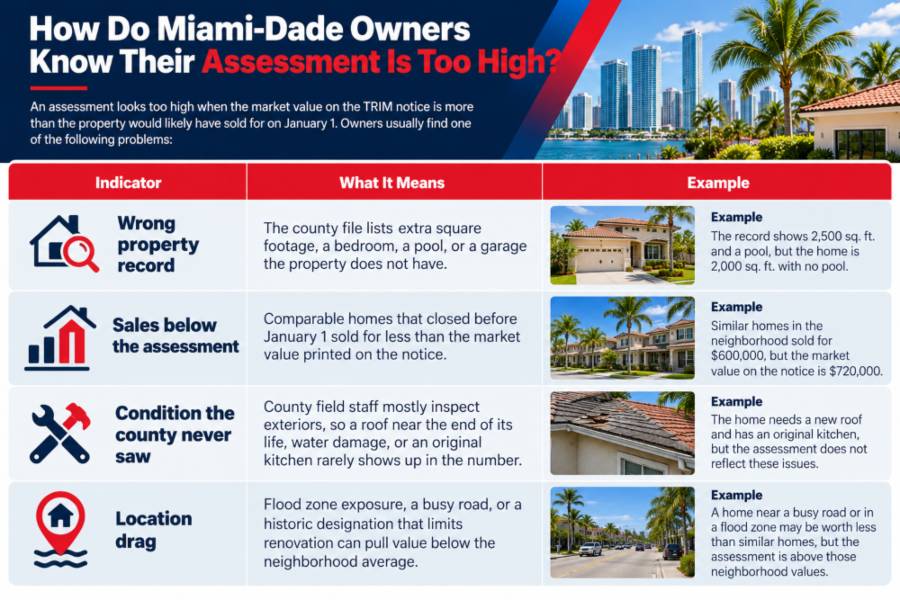
An assessment looks too high when the market value on the TRIM notice is more than the property would likely have sold for on January 1. The Property Appraiser of Miami-Dade County values every parcel each year using a mass appraisal model, and single-property errors slip through.
Owners usually find one of these problems:
Florida gives Miami-Dade owners three routes: an informal review with the Property Appraiser, a petition to the Value Adjustment Board, and a lawsuit in circuit court. The informal review is optional under s. 194.011(2), and each route runs on its own clock.
The Property Appraiser opens an interview period each August after TRIM notices go out. Owners call 305-375-4712 or submit the Assessment Review Form, and staff aims to answer within three to five business days, according to the Property Appraiser’s assessment page.
The office asks for date-stamped photos, repair estimates, insurance records, and comparable sales. Commercial owners add a January 1 rent roll, a 12-month operating statement, and any appraisal.
The Department of Revenue’s taxpayer guide to VAB petitions confirms that this review does not extend the 25-day petition deadline, so owners file a petition while it runs.
The Value Adjustment Board works under the Clerk of the Court and Comptroller and is independent of the Property Appraiser.
Owners file online through the Clerk’s VAB system or at the Stephen P. Clark Center, Suite 1720, and the Clerk’s VAB office treats a petition as filed only when it is received.
An owner who misses the deadline can file late with a written explanation, but the petition is heard only if the board finds good cause.
A circuit court case starts the dispute over from scratch, and owners do not need a VAB petition first.
Under s. 194.171, the suit generally must be filed within 60 days after the assessment is certified for collection, and the owner first pays the tax admitted in good faith.
Those conditions are jurisdictional, so it’s worth consulting a property tax attorney first.
If you’re ready to get started, call us now!
The right step depends on what is wrong with the assessment and how much time remains, and a protest appraisal belongs only when the numbers support it.
| Owner’s Situation | Best Next Step | Timing |
| County record lists wrong size, rooms, or features | Ask the Property Appraiser to correct the record | Any time of year; before the petition deadline for the current year |
| Value looks high, but sales evidence is mixed | Informal review with comparable sales | Interview period after the TRIM notice; the 25-day clock keeps running |
| Clear gap between the TRIM value and closed sales | VAB petition, with an appraisal when the savings math works | Within 25 days after the TRIM notice is mailed |
| Homestead with a large Save Our Homes difference | Check whether a lower market value would change assessed value at all | Before paying for an appraisal |
| 2026 petition deadline already missed | Ask the Clerk about late filing, consult an attorney on circuit court, or prepare for 2027 | Circuit court: generally 60 days after certification for collection |
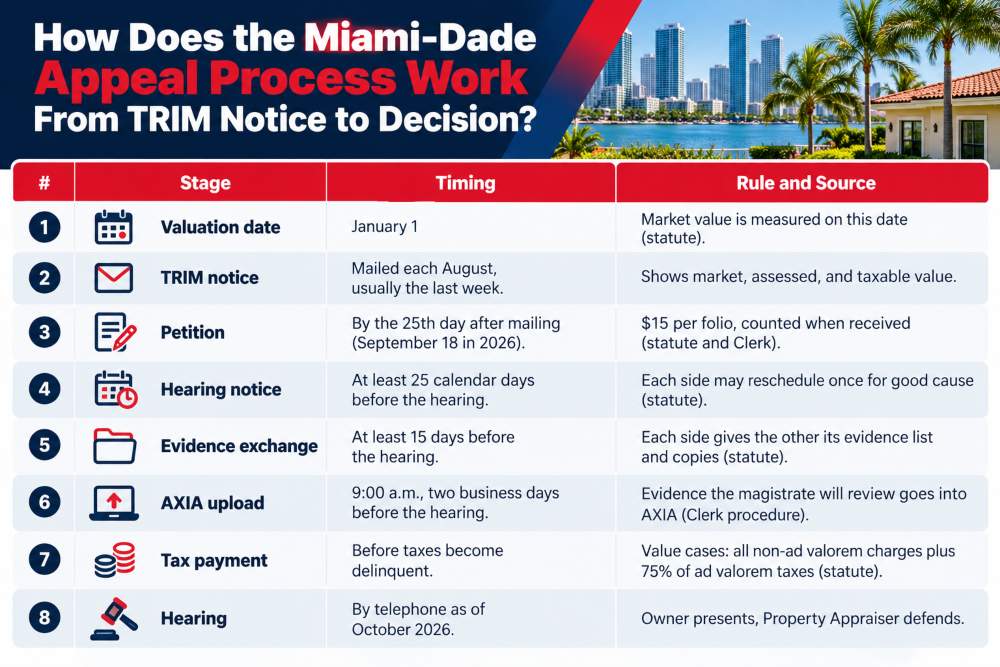
The Miami-Dade appeal follows the Value Adjustment Board calendar from January 1 to a written board decision, and the table marks which steps come from statute and which from Clerk procedure.
| Stage | Timing | Rule and Source |
| Valuation date | January 1 | Market value is measured on this date (statute) |
| TRIM notice | Mailed each August, usually the last week | Shows market, assessed, and taxable value |
| Petition | By the 25th day after mailing (September 18 in 2026) | $15 per folio, counted when received (statute and Clerk) |
| Hearing notice | At least 25 calendar days before the hearing | Each side may reschedule once for good cause (statute) |
| Evidence exchange | At least 15 days before the hearing | Each side gives the other its evidence list and copies (statute) |
| AXIA upload | 9:00 a.m., two non-holiday workdays before the hearing | Evidence the magistrate will review goes into AXIA (Clerk procedure) |
| Tax payment | Before taxes become delinquent | Value cases: all non-ad valorem charges plus 75% of ad valorem taxes (statute) |
| Hearing | By telephone as of October 2026 | Owner presents, Property Appraiser defends |
The exchange rule in s. 194.011(4) is mandatory, yet a late exchange does not automatically bar the owner’s evidence. Evidence the Property Appraiser requested in writing and the owner withheld is barred under s. 194.034(1)(h).
Missing the payment carries a firmer consequence. Under s. 194.014, the board must deny a value petition in writing by April 20 when the 75% payment was not made. Owners contesting an exemption or classification pay the amount they admit in good faith instead.
Twenty-five days pass quickly; Home Value Inc returns tax protest reports within three to five business days of inspection, so owners can beat the deadline.
Evidence holds up when adjusted market data shows the county figure misses just value on January 1, though no document guarantees a result. The legal test sits in s. 194.301, and it works in two layers.
The Property Appraiser’s assessment is presumed correct only when the office proves, by a preponderance of the evidence, that it followed s. 193.011 and accepted appraisal practice.
The owner must then prove, by the same standard, that the assessed value does not represent just value after any caps, or that the office valued the parcel differently from comparable property.
When the owner succeeds, the board sets a value only if the record holds competent evidence meeting s. 193.011; otherwise the matter goes back to the Property Appraiser.
The special magistrate on a value case is a state-certified real estate appraiser, normally with five or more years of valuation experience under s. 194.035, so automated estimates get tested hard.
| Evidence | What It Proves | Where It Falls Short |
| Certified appraisal dated January 1 | Market value from sales closed before January 1, with adjustments | Costs $350 to $550 for most homes; no guaranteed outcome |
| Printout of closed sales | General price level in the neighborhood | No adjustments for size, condition, or location |
| Photos, repair estimates, insurance records | Condition the county could not see | Does not turn damage into a value figure |
| Corrected property record | Errors in size, rooms, or features | Fixes data, not market value |
| Online estimate such as a Zestimate | Rough automated value | No inspection and no adjustments |
| Rent roll and operating statement | Income a commercial property earns | Needs an income approach analysis to become value |
An appeal appraisal carries a January 1 effective date even when signed months later. Income property such as offices, warehouses, and retail buildings is usually valued on the income it earns as well as nearby sales.
An appraisal is optional, and it makes financial sense only when the likely drop in taxable value, not just market value, would save more than the fee. The fee is spent whether or not the magistrate agrees.
The Property Appraiser’s value definitions separate three figures: market value is the January 1 estimate, assessed value is market value after the applicable cap, and taxable value is assessed value minus exemptions, which can differ between school and non-school levies.
For example, at a combined rate of 20 mills, each $10,000 cut from taxable value saves $200 a year, so a $40,000 drop saves $800.
Home Value Inc’s fees range from $400 to $550 for a single-family home and from $350 to $500 for a condo.
| Property Type | Annual Assessment Cap | What a Lower Market Value Changes |
| Homestead residence | 3% or CPI, whichever is lower (2.9% for 2025) | Taxes drop only when proven market value falls below the capped assessed value |
| Non-homestead residential | 10% for non-school levies | School taxes drop at once; other levies drop when value falls below the capped figure |
| Commercial property | 10% for non-school levies | Same as non-homestead residential |
Take a hypothetical homestead with a $700,000 market value and a $420,000 capped assessed value. Cutting market value to $650,000 leaves assessed value at $420,000, so that year’s bill does not move.
Rental investors see school taxes drop right away, while city and county levies fall only when proven value drops below the 10% capped figure.
Owners who call get a review of the TRIM notice and closed sales first. Jhovan F. Rojas tells the owner, before collecting any fee, when an appraisal is unlikely to pay off.
The board acts on the special magistrate’s recommendation and issues a written decision within 20 calendar days after its last session day, under s. 194.034(2). When value drops, the Tax Collector refunds the overpaid tax.
The Clerk’s VAB page puts typical refund timing at six to eight weeks after the hearing, though timing varies. Under s. 194.014(2), the refund earns interest at the bank prime loan rate set each July 1, counted from the date the taxes would have become delinquent.
An owner who believes the magistrate made a mistake of law or fact can request reconsideration under the Clerk’s written procedures, and the circuit court route stays open within its deadlines.
A win covers one tax year, so owners review each TRIM notice on its own and keep the appraisal methods from the last case on file.
What is the deadline to appeal property taxes in Miami-Dade?
The deadline is the 25th day after the Property Appraiser mails the TRIM notice, under s. 194.011(3)(d). The 2026 Miami-Dade deadline was September 18, 2026. The next window opens when Miami-Dade mails 2027 TRIM notices, usually in the last week of August.
How much does it cost to file a property tax appeal in Miami-Dade?
The Miami-Dade Value Adjustment Board charges $15 per folio when the petition is filed. Condominium and cooperative associations filing a joint petition pay no more than $5 per unit. An independent appraisal for the hearing is an optional, separate cost.
Can I appeal my property taxes without an appraisal?
Yes. Owners can present closed sales, photos, repair estimates, and record corrections on their own. An adjusted appraisal adds stronger market evidence, but the owner still carries the burden of proof, and neither route guarantees that the special magistrate will lower the value.
Do I have to pay my property taxes while the appeal is pending?
Yes. Value petitioners pay all non-ad valorem charges and at least 75% of ad valorem taxes before delinquency under s. 194.014. Owners contesting an exemption or classification pay the amount they admit in good faith. If they miss the payment, the petition is denied.
Can I still appeal if I missed the TRIM notice deadline?
Possibly. A late petition needs a written explanation, and the board hears it only after finding good cause. A circuit court suit under s. 194.171 has its own deadline, generally 60 days after the roll is certified for collection, so attorney advice helps.
Does a homestead exemption affect a property tax appeal in Florida?
Yes. Save Our Homes limits yearly growth in homestead assessed value to 3% or CPI, whichever is lower. When market value sits far above the capped figure, as it can in long-held Coral Gables homes, a market value cut may not change that year’s bill.
Can a condo association appeal property taxes for all units?
Yes. Under s. 194.011(3)(e), a condominium association with board approval can file one joint petition for units the Property Appraiser finds substantially similar. Owners get at least 14 days’ notice to opt out, and the Miami-Dade fee is capped at $5 per unit.
Can someone represent me at a Miami-Dade VAB hearing?
Yes. Under s. 194.034, owners may send a Florida Bar attorney, a licensed real estate appraiser or broker, a licensed CPA, or an employee. A friend or relative can appear with unpaid written authorization, and a power of attorney covers one assessment year.
The appeal decision comes down to three checks: an accurate county record, a TRIM market value above sales that closed before January 1, and a market value cut that would actually lower taxable value, which homestead caps often prevent. When all three point to a real gap, a petition backed by adjusted evidence is worth filing.
An inflated assessment costs money every year it stands; talk to Rojas at Home Value Inc about a January 1 appraisal before August.
About the Author
South Florida Residential Appraiser · Expert Witness · Residential Valuation Specialist
Jhovan Rojas is a South Florida residential real estate appraiser with more than 20 years of experience valuing residential properties throughout Miami-Dade, Broward, and Palm Beach Counties. His appraisal experience spans multiple real estate market cycles, including the foreclosure-driven downturn of the late 2000s, the subsequent recovery period, and the rapid appreciation that followed the COVID-19 housing boom.
Throughout his career, Jhovan has appraised thousands of residential properties, including single-family homes, condominiums, multi-family residences, luxury estates, waterfront properties with boating access, and complex high-value residential assets. His expertise includes residential valuation, appraisal review, market analysis, lender compliance review, and expert witness services for litigation involving real estate valuation disputes.
In addition to performing residential appraisals, Jhovan has conducted appraisal reviews for lending institutions, supervised and mentored trainee appraisers, and provided expert testimony in divorce and property-related legal matters. He is also a frequent speaker for Realtor and broker education programs, where he shares insights on valuation methodology, appraisal standards, market trends, and factors influencing residential property values throughout South Florida.
Drawing on decades of hands-on appraisal experience, Jhovan helps homeowners, attorneys, lenders, real estate professionals, and property investors make informed decisions based on credible, well-supported valuation analysis.
Home Value Inc. performs residential and commercial appraisals for its clients in greater Miami-Dade County and the following cities in South Florida. We provide services to the following cities -